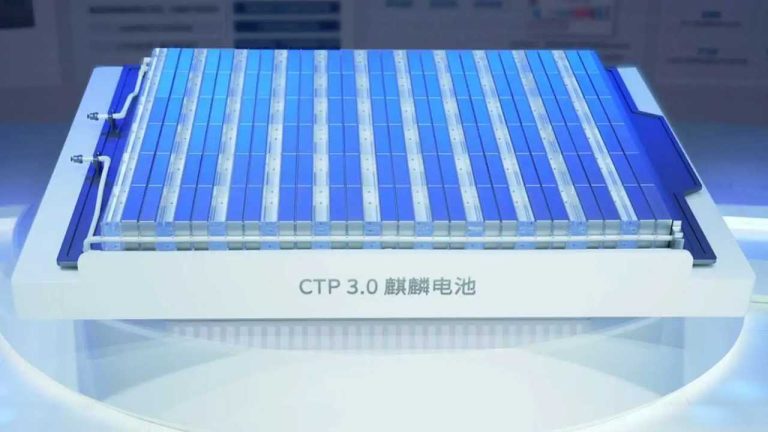
Global electric vehicle battery usage surged nearly 20% in the first nine months of 2026, with Chinese manufacturers further strengthening their dominance. CATL and BYD together accounted for over half of all battery installations worldwide, according to new data from SNE Research.
Global Battery Market Sees Strong Growth
From January to September 2026, global EV battery usage reached 994.5 GWh, marking a 19.7% increase compared to the same period last year. September alone set a new monthly record with 145.1 GWh installed, though the year-on-year growth rate for the month slowed to 15.8%. These figures include battery electric vehicles, plug-in hybrids, and conventional hybrids.
CATL and BYD Dominate Market Share
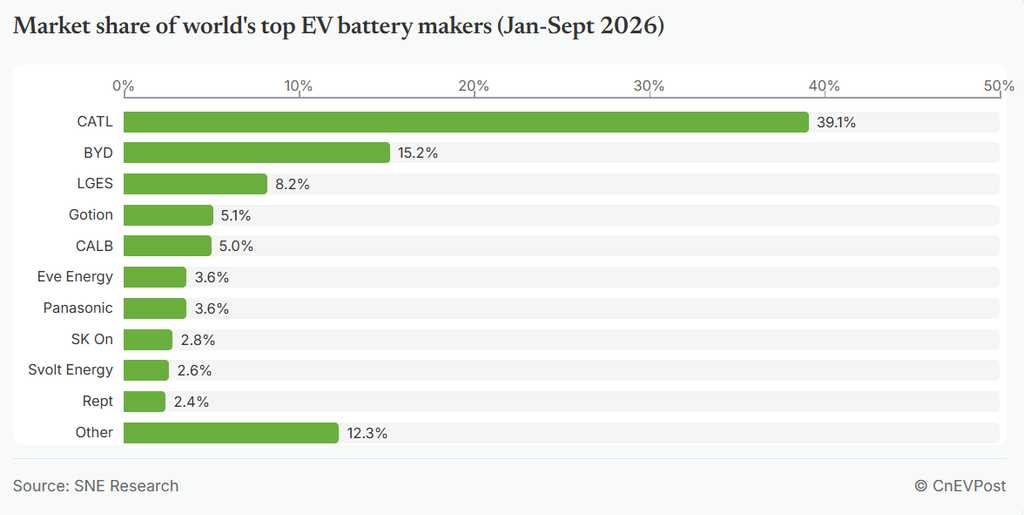
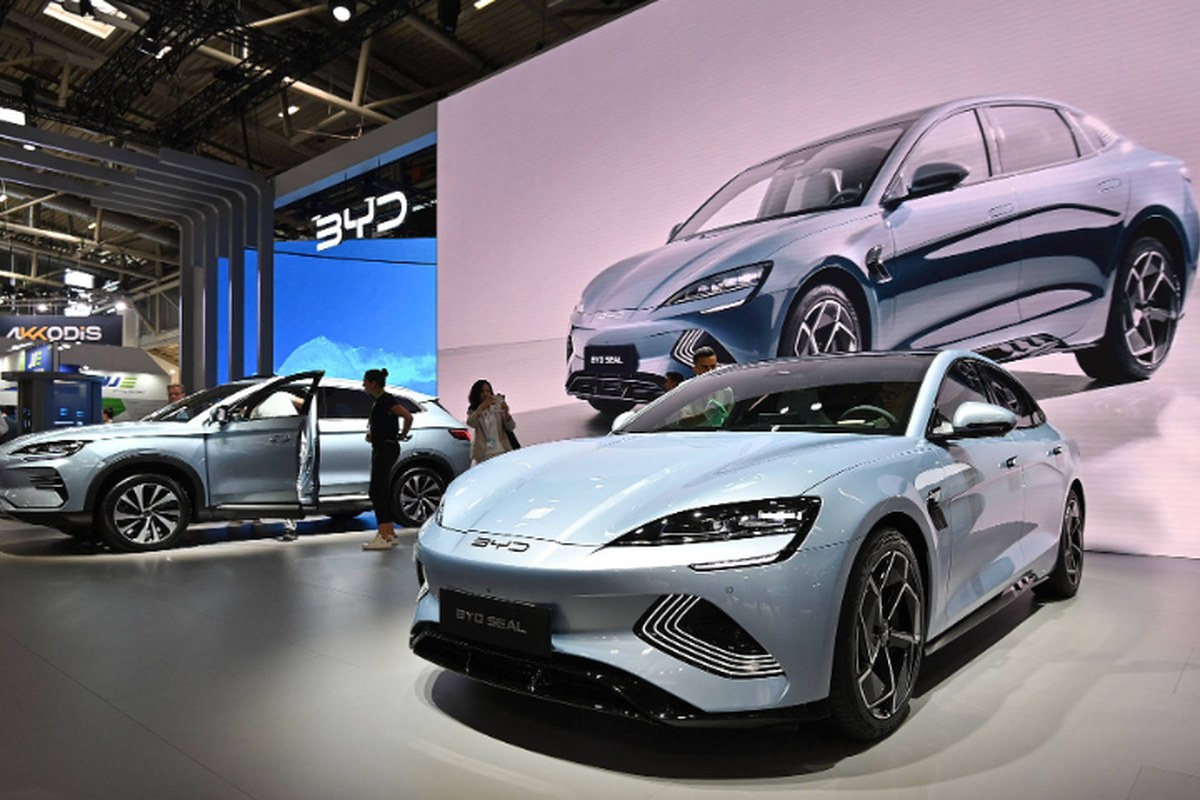
CATL retained its position as the world’s largest EV battery supplier, installing 389.2 GWh—up 24.9% year-on-year—and increasing its global share to 39.1%. BYD followed with 150.9 GWh installed, a 7.4% rise from last year, though its market share slipped to 15.2%. Combined, CATL and BYD held 54.3% of the global market, a figure largely unchanged from a year earlier.
CATL continued to expand its overseas customer base, while BYD’s battery supply remained closely linked to its own vehicle sales. SNE Research noted that the gap in growth rates between the two companies widened to 17.5 percentage points.
Performance of Other Leading Battery Makers
LG Energy Solution (LGES) ranked third with 81.9 GWh installed, up just 0.7% year-on-year, and saw its market share fall to 8.2%. LGES continued to supply major automakers including Tesla, GM, Hyundai Motor Group, and Volkswagen. Its installations grew in Europe and Asia but dropped sharply in North America.
Gotion High-tech climbed to fourth place with 50.3 GWh, up 48.1%, narrowly surpassing CALB, which installed 50.1 GWh. Eve Energy rose to sixth place with 36.0 GWh, up 60.4%. Panasonic slipped to seventh with 35.6 GWh, down 0.8%, while SK On ranked eighth with 28.3 GWh, down 18.1%. Svolt Energy and Rept Battero Energy rounded out the top ten, with Rept Battero Energy’s installations surging 118.7% to 24.2 GWh.
Regional Trends and Battery Technology
China remained the largest market, with battery installations rising 16.2% year-on-year to 567.8 GWh. Europe saw a 33.1% increase, while Asian markets outside China grew 74.1% and South America expanded 176.8%. In contrast, North America experienced a 24.3% decline, with installations falling to 85.9 GWh.
The share of lithium iron phosphate (LFP) batteries increased to 57.7%, up from 52.5% a year earlier. The average battery capacity per vehicle also rose by 11.2% to 39.7 kWh.
Why this matters
The latest data highlights the growing influence of Chinese battery manufacturers in the global EV sector, with seven Chinese companies now holding a combined 73.0% share of the market. The continued expansion of CATL and BYD, alongside rapid growth from other Chinese firms, is shaping the competitive landscape for automakers and battery suppliers worldwide.
Regional shifts in battery installations and the rising adoption of LFP technology are also influencing the types of batteries used in new electric vehicles, impacting both performance and supply chains.
What this means for buyers
Buyers can expect ongoing changes in battery technology and supply as leading manufacturers expand their reach and new chemistries like LFP become more prevalent. Regional differences in battery adoption may affect vehicle availability and specifications, depending on where vehicles are produced and sold.
Key Specs
- Global EV battery usage (Jan-Sep 2026): 994.5 GWh
- CATL battery installations: 389.2 GWh
- CATL global market share: 39.1%
- BYD battery installations: 150.9 GWh
- BYD global market share: 15.2%
- Combined share of 7 Chinese companies in top 10: 73.0%
- Combined share of 3 South Korean companies in top 10: 12.6%
- Share of LFP batteries: 57.7%
Images sourced from: electrek.co, globaltimes.cn